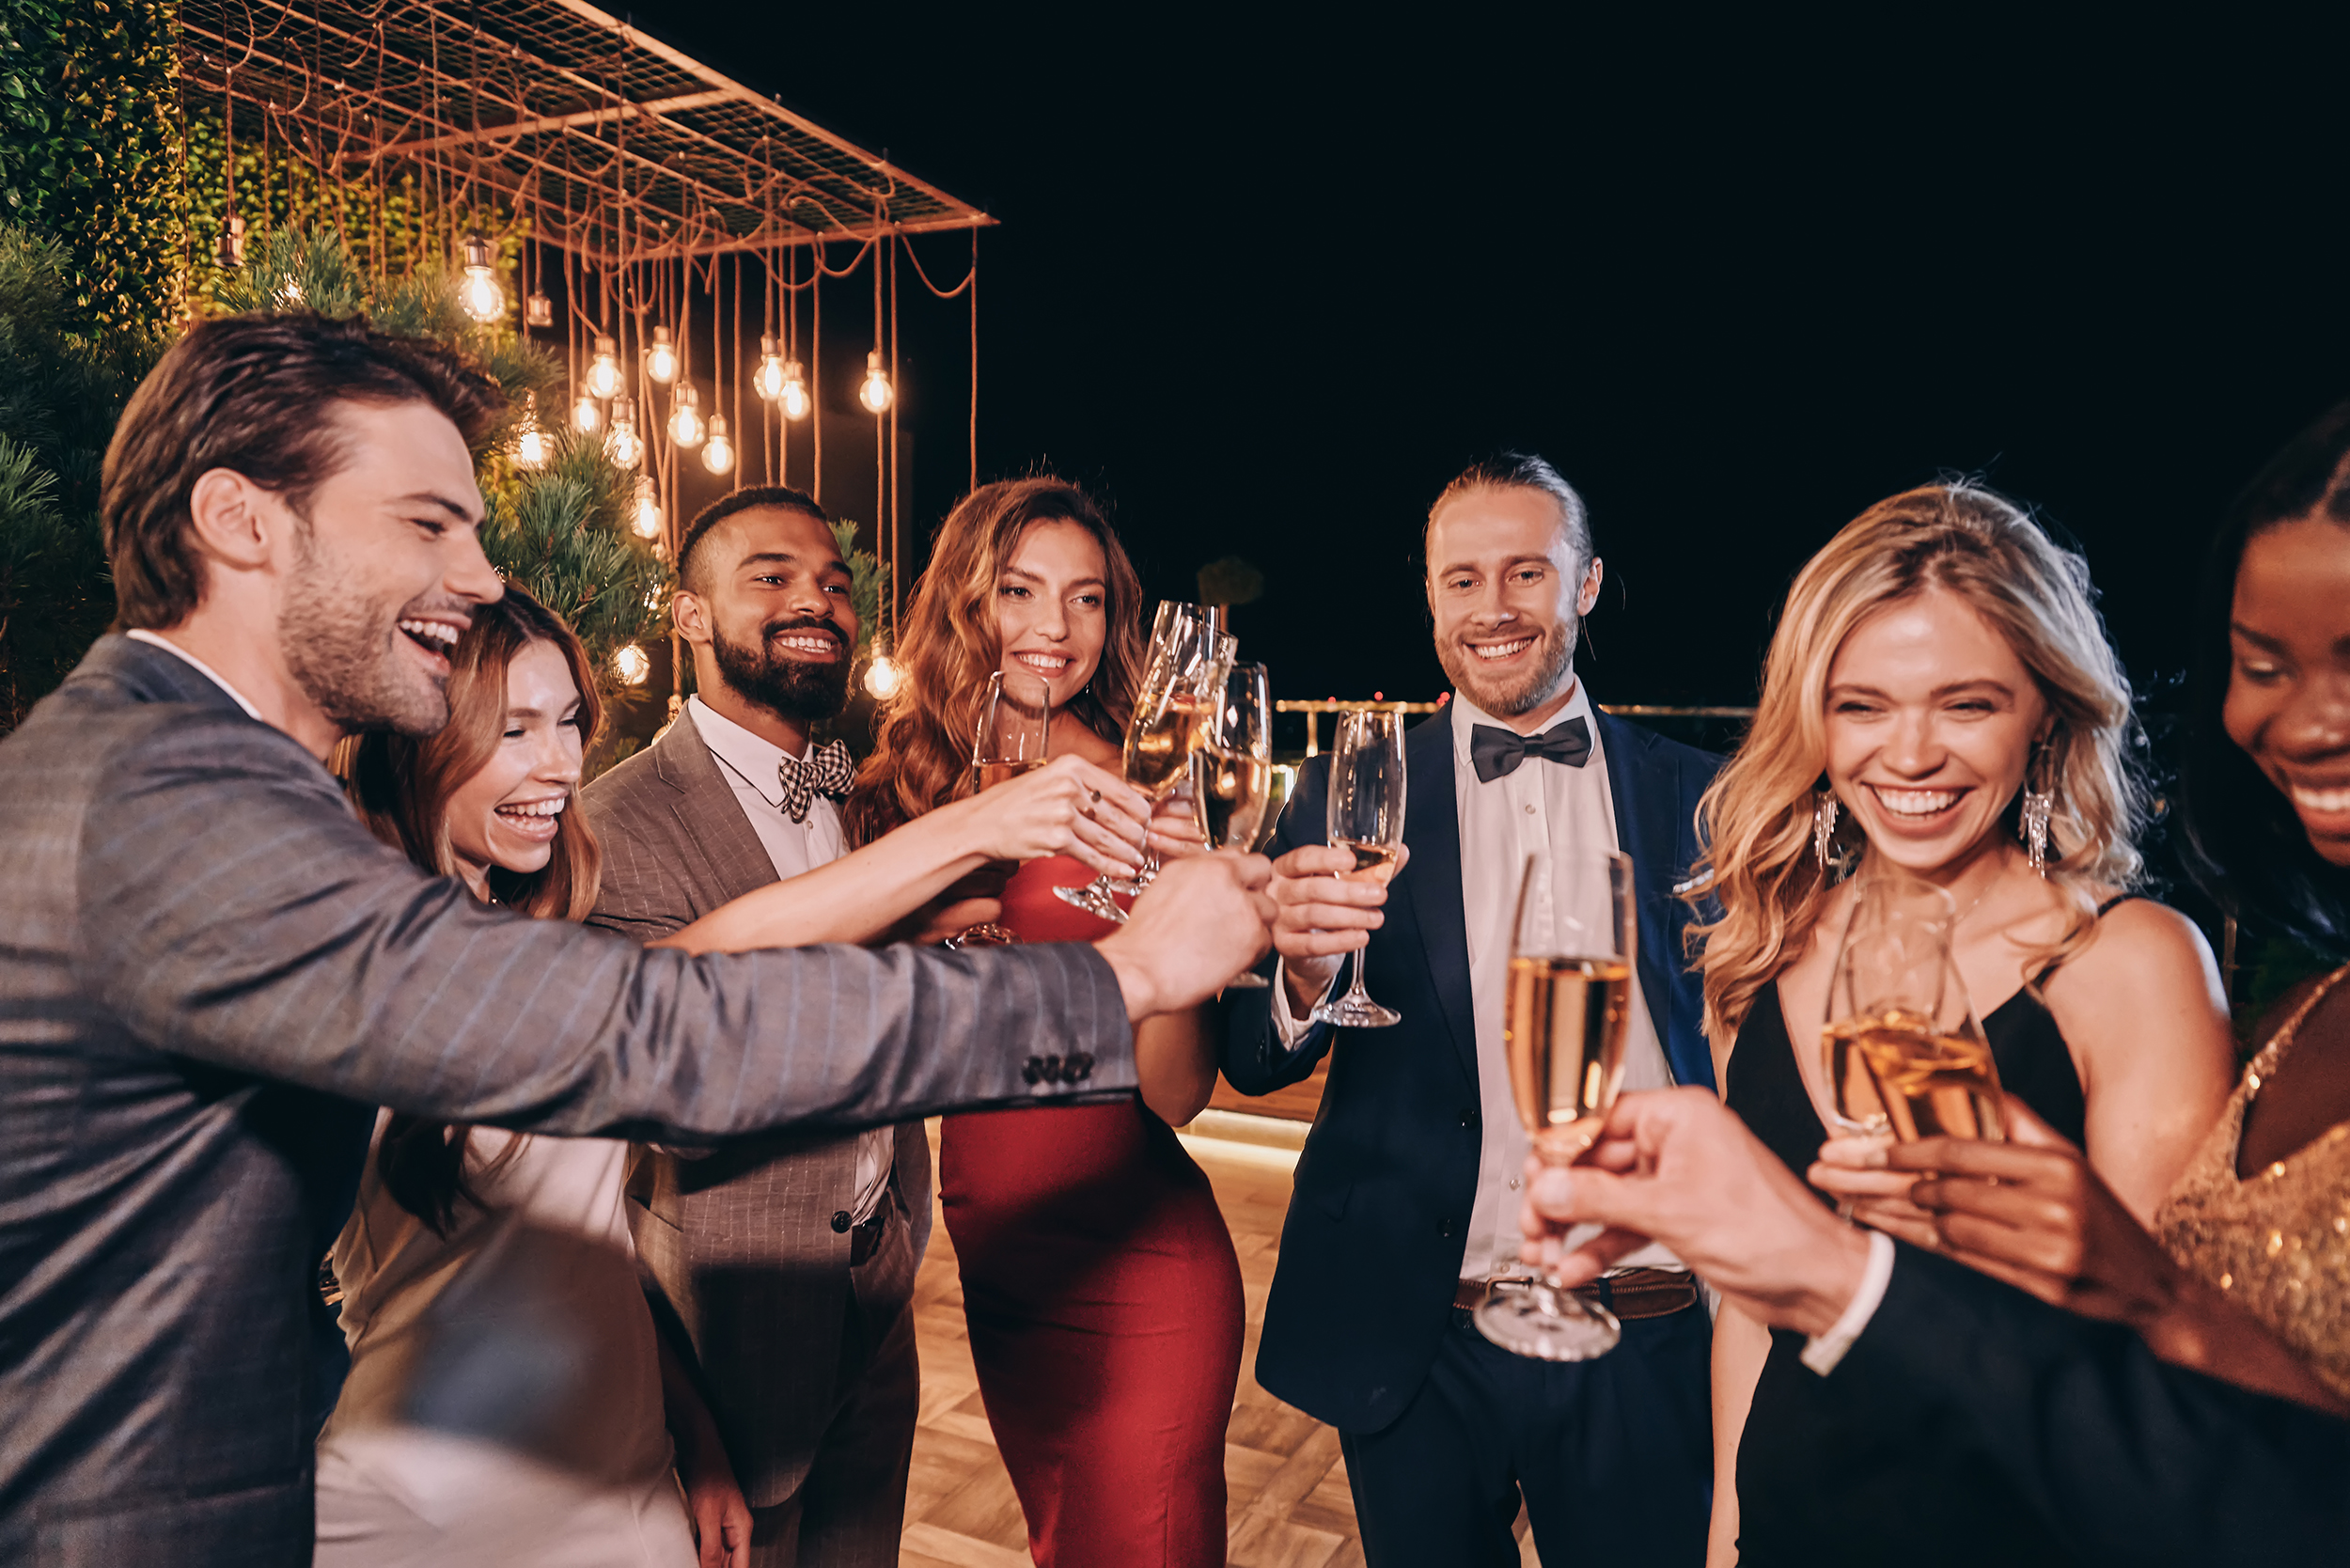
The holiday season is here once again, and for some workplaces, that means holiday parties. Although the rules for deducting business entertainment expenses changed several years ago, you may still qualify for some holiday party write-offs for this year, possibly even the entire cost. As you plan, understand the rules so you can avoid potentially costly missteps.
The Rules Before and Since the TCJA
Before the Tax Cuts and Jobs Act (TCJA), businesses could deduct 50% of certain entertainment costs, such as tickets for clients after contract negotiations. Although the TCJA permanently eliminated deductions for entertainment expenses starting in 2018, a key exception remains: If your business holds a company-wide party for employees, you may be able to deduct 100% of the cost. Some examples of potentially eligible expenses are:
-
- Food and beverages,
- Decorations,
- Venue and furniture rentals,
- Prizes and giveaways, and
- DJ or live band fees
However, for such expenses to be deductible, the party must not be “lavish and extravagant,” and the entire staff must be invited, not just management. Also, if your staff consists only of family members, your party costs aren’t deductible. Under family attribution rules, the IRS views this as an event for owners or officers rather than employees.
Non-employee Guests
Inviting friends, family, clients or business associates complicates matters. Here’s an example:
In December 2025, a company invites 60 employees and their partners to a holiday party. Forty employees and their plus-ones attend. In addition, the owner invites five friends, three business associates, and two independent contractors, who all attend with their plus-ones. The total party tab is $10,000, or $100 per person, for 100 guests.
On its 2025 corporate return, the company may deduct $8,000 (the $100 cost for each of the 40 employees and their 40 plus-ones). The $2,000 cost for the other 20 guests is considered personal and not deductible. Independent contractors are treated as non-employees for this purpose, even if they perform similar work.
The takeaway is that the more non-employees you invite, the less you can deduct.
Safeguarding Your Deductions
As always, keep detailed receipts and records. If the IRS questions your deductions, it may request documentation. Reduce audit risk by keeping expenses reasonable relative to company size and limiting personal guests.
Finally, contact the office with your questions. By seeking professional guidance in advance, you can show your workforce your holiday appreciation while maximizing your deductions and staying compliant with current tax law.