

More Taxpayers May Qualify for the Casualty Loss Deduction

Jan 1, 2026 | Tax & Accounting

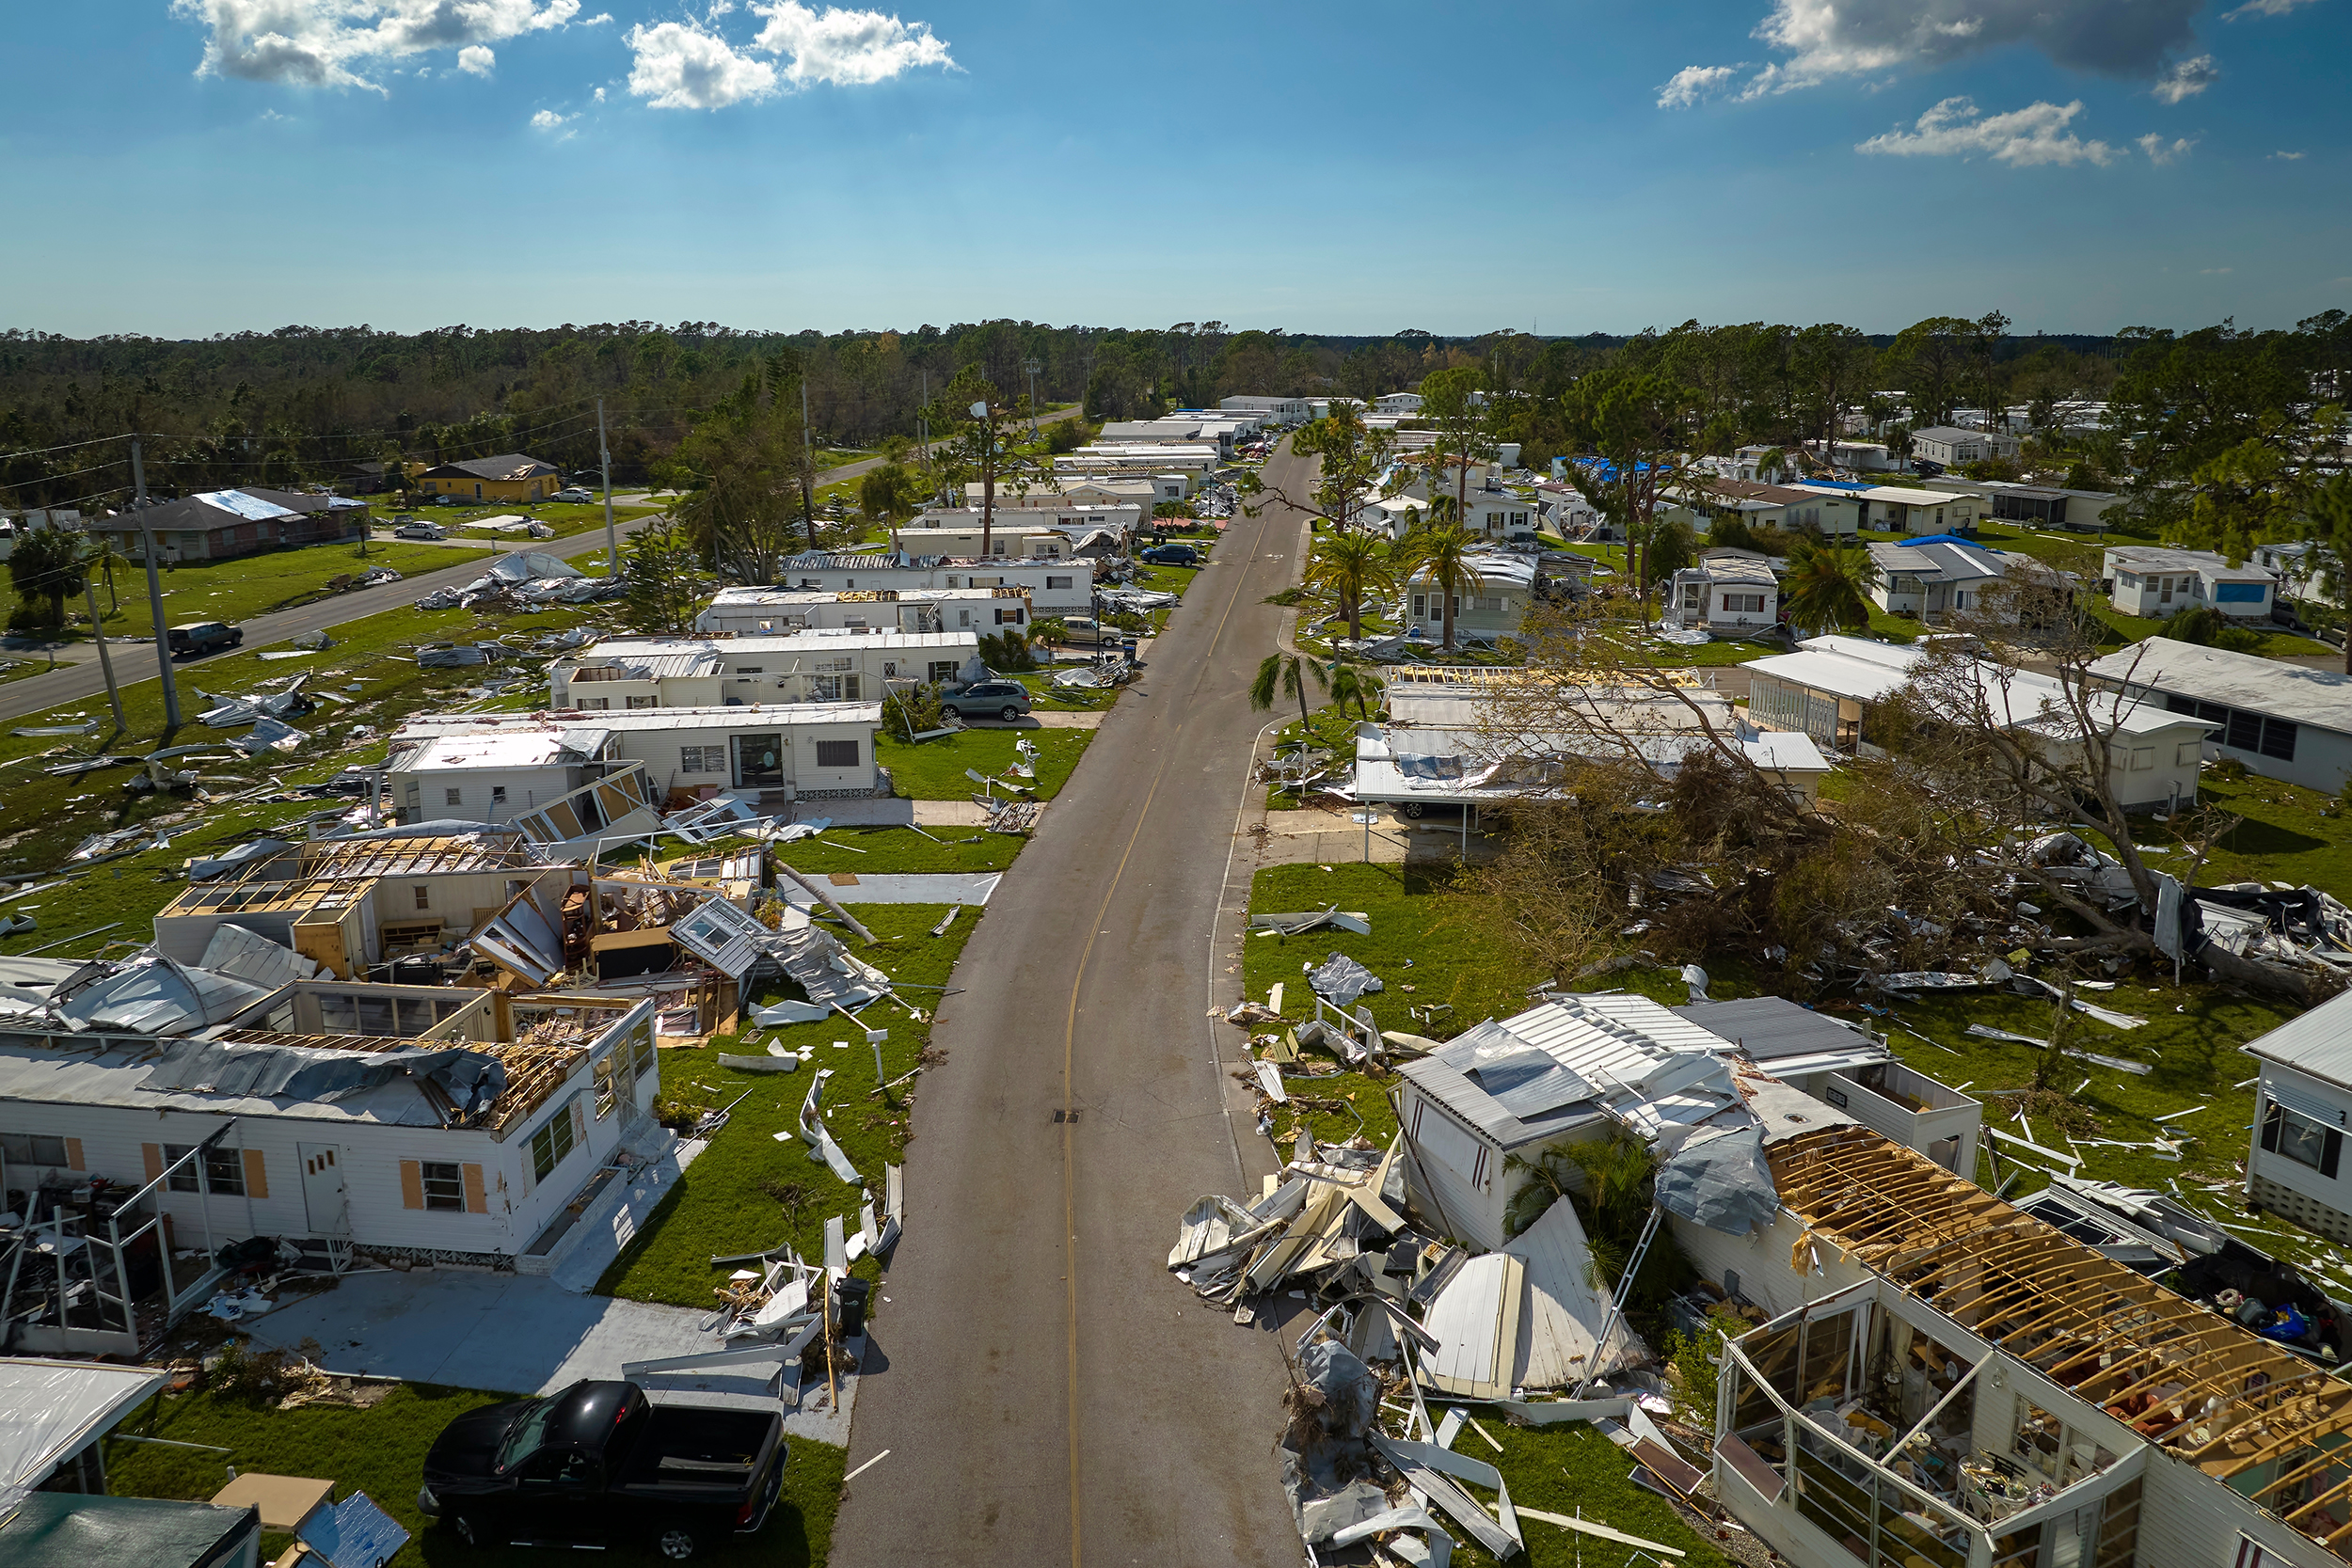
Starting in 2026, personal casualty loss deductions will no longer be limited to federally declared disasters. Certain state-declared disasters will also be eligible. For a disaster to qualify, the governor (or D.C. mayor) and the U.S. Treasury Secretary must agree that the damage is severe enough to apply these rules. Now more taxpayers affected by natural disasters or by fires, floods or explosions, regardless of the cause, may qualify.

Note that taxpayers can still claim personal casualty losses not attributable to federally or state-declared disasters, but only to the extent of any personal casualty gains. Need guidance? Contact the office for help.


Recent Posts

Get Ahead of Taxable Benefits

Get Ahead of Taxable Benefits

As year end approaches, businesses have plenty of tax and payroll tasks competing for attention. One easy-to-overlook area is employee and owner benefits. Identifying taxable benefits before the final payroll runs of 2026 can help prevent reporting errors, payroll tax...

Could You Owe the NIIT?

Could You Owe the NIIT?

Selling a highly appreciated investment late in the year could trigger an additional tax cost: the 3.8% net investment income tax (NIIT). If you’re considering a significant transaction before January 1, first estimate the potential tax impact and evaluate planning...

Tax-Smart Building Improvements

Tax-Smart Building Improvements

If your business is planning improvements to a building before year end, careful planning may allow you to maximize your 2026 tax deduction. A special safe harbor can allow qualifying small businesses to deduct such expenditures currently — but only if expenses don’t...

Charitable Givers Get a New Tax Break

Charitable Givers Get a New Tax Break

Beginning in 2026, taxpayers who take the standard deduction may deduct up to $1,000 of qualifying charitable contributions, or up to $2,000 for married couples filing jointly. Only cash contributions qualify, such as gifts made by check, debit or credit card, payment...

