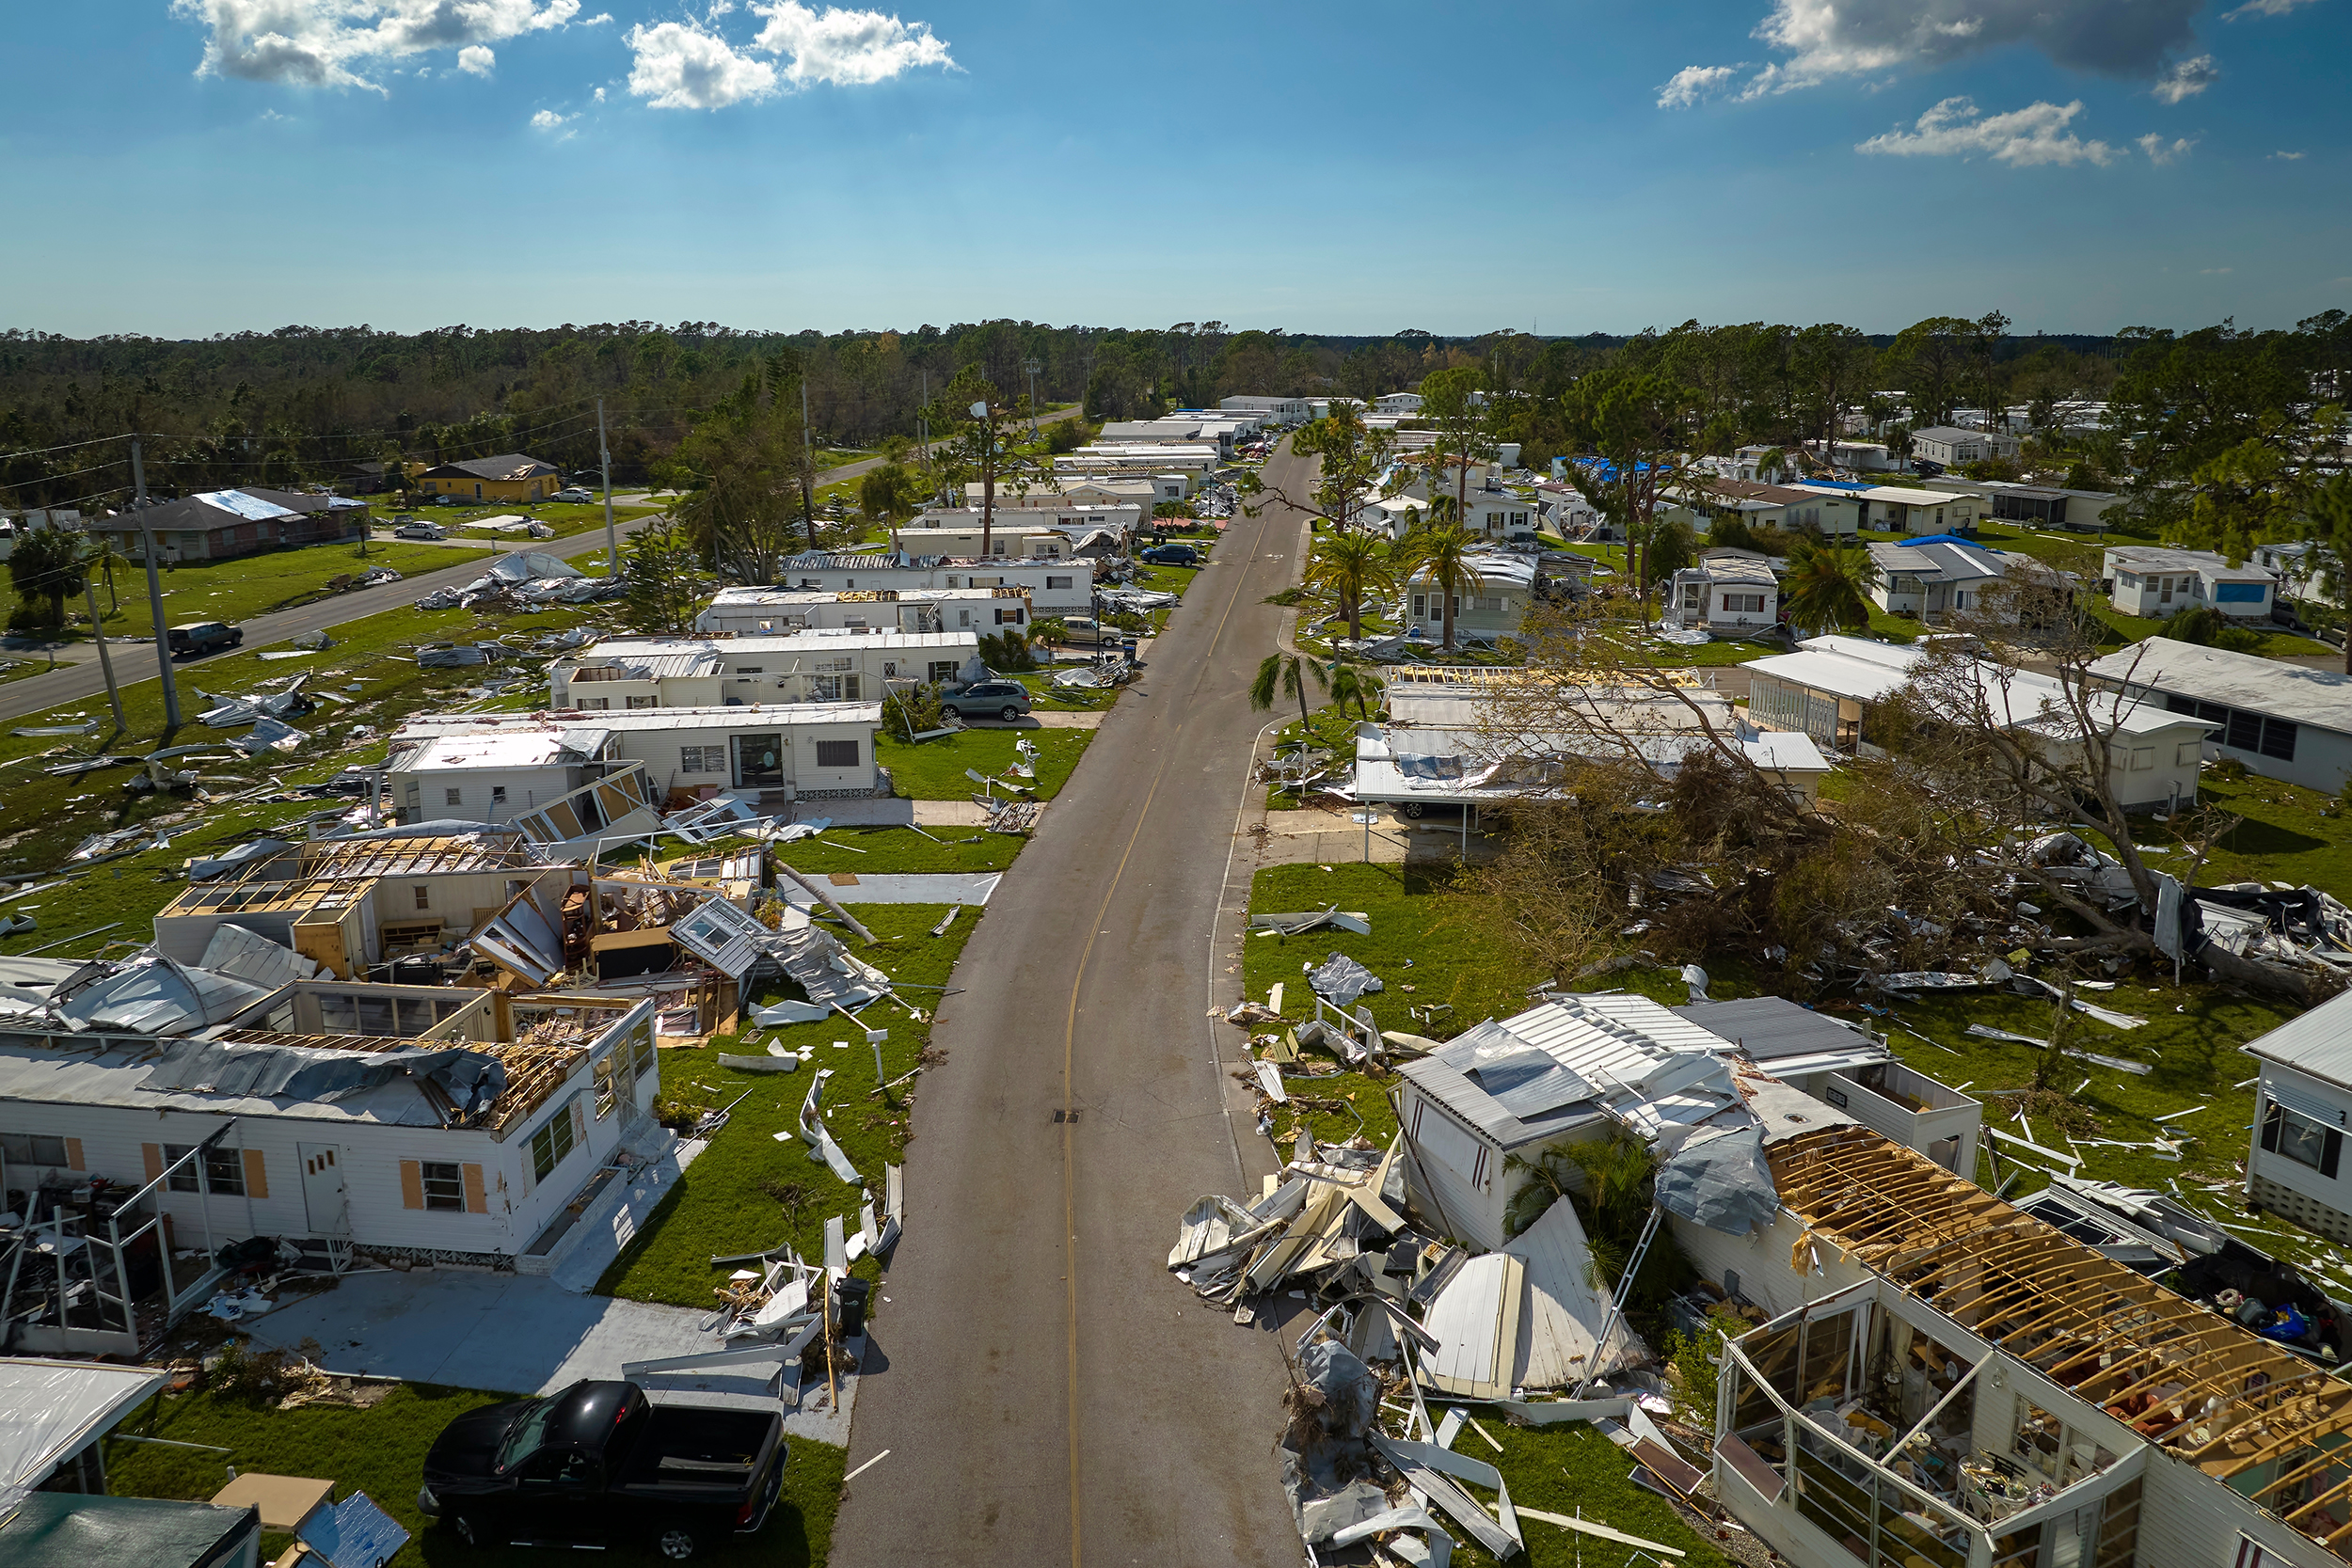
More Taxpayers May Qualify for the Casualty Loss Deduction

Jan 1, 2026 | Tax & Accounting

Starting in 2026, personal casualty loss deductions will no longer be limited to federally declared disasters. Certain state-declared disasters will also be eligible. For a disaster to qualify, the governor (or D.C. mayor) and the U.S. Treasury Secretary must agree that the damage is severe enough to apply these rules. Now more taxpayers affected by natural disasters or by fires, floods or explosions, regardless of the cause, may qualify.

Note that taxpayers can still claim personal casualty losses not attributable to federally or state-declared disasters, but only to the extent of any personal casualty gains. Need guidance? Contact the office for help.
Recent Posts

Could Bad Debts Lower Your 2026 Taxes?

Could Bad Debts Lower Your 2026 Taxes?

When customers or others don’t pay what they owe your business, you may be able to claim a bad debt deduction to help offset the financial loss. But it isn’t automatic. Businesses must satisfy specific federal tax rules and maintain adequate records to support the...

4 Tax-Smart Investment Moves Before Year End

4 Tax-Smart Investment Moves Before Year End

As the end of 2026 approaches, look beyond investment performance and consider how taxes may affect your overall returns. Although tax considerations generally shouldn’t drive investment decisions, a year-end portfolio review may identify opportunities to reduce your...

Make the Most of Your HSA Tax Benefits

Make the Most of Your HSA Tax Benefits

If you’re eligible to contribute to a Health Savings Account (HSA), consider taking a closer look at your contribution strategy. You may be able to reduce your 2026 taxes while strengthening your long-term financial security. Although many people use HSAs to pay...

Ready Your Books for Tax Season

Ready Your Books for Tax Season

One of the most common bookkeeping mistakes business owners make is mixing business and personal finances. Addressing this issue before year end can simplify tax preparation, improve the accuracy of your financial records and help reduce the risk of IRS questions....