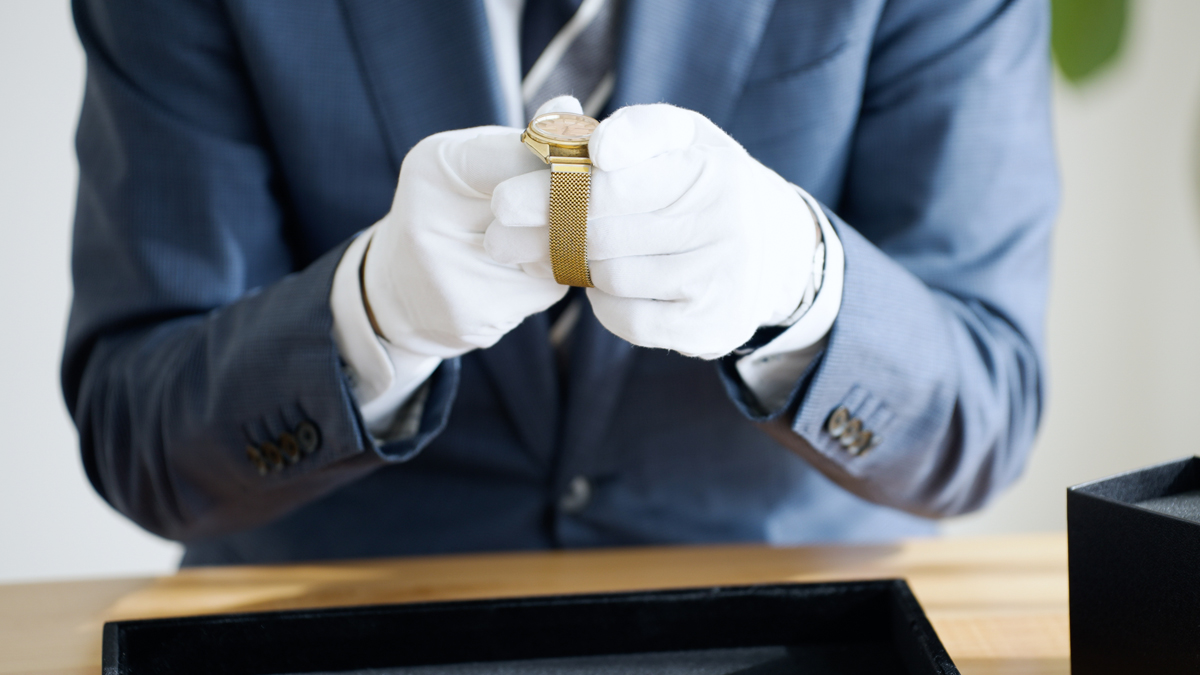
Whether you’re in the process of making a retirement or estate plan or you intend to donate property to charity, you’ll need to know the value of your assets. For many hard-to-value items, such as closely held business interests, real estate, art and collectibles, an appraisal may be necessary.
Retirement and Estate Planning
To enjoy a comfortable retirement, you’ll need to calculate the income that can support your lifestyle when you’re no longer working. This means understanding the value of the assets you own. Once you have this information, you may decide to move your retirement date up or back.
Knowing the value of your assets is also necessary to assess whether you’ll potentially be subject to gift and estate taxes. It also allows you to identify strategies for minimizing or eliminating those taxes. In addition, without appraisals of hard-to-value assets, it’s nearly impossible to divide your overall property equally among your children (if that’s your wish).
Appraisals may also be necessary to avoid running afoul of tax basis consistency rules. The rules are intended to prevent heirs from arguing that estate property was undervalued, which would raise their basis for income tax purposes. According to these rules, the income tax basis of inherited property equals the property’s fair market value as finally determined for estate tax purposes. Appraisals can help ensure that your heirs receive the basis they deserve.
Gifts and Charitable Giving
The IRS has an unlimited amount of time to challenge the value of gifts for gift and estate tax purposes, unless they’re “adequately disclosed,” which generally binds the IRS to a three-year statute of limitations. A qualified professional appraisal with a timely filed gift tax return is the best way to disclose the value of a gift of a hard-to-value asset.
Charitable gifts of property valued at more than $5,000 (other than publicly traded securities) must be substantiated with a qualified appraisal by a qualified appraiser. This means that the appraiser meets certain education and experience requirements.
Know What You Have
Without appraisals of your hard-to-value assets, it’s difficult to develop a realistic financial plan, to create an estate plan that will achieve your desired results and to avoid unwelcome tax liabilities. Asset values can fluctuate dramatically over time, so make sure you get updated appraisals periodically.